
The transactions show a debit balance of 500 for rent and a credit balance of 500 for the bank. A double entry system https://x.com/BooksTimeInc is considered complex and is employed by accountants or CPAs (Certified Public Accountants). The information they enter needs to be recorded in an easy to understand way. This is why a T account structure is used, to clearly mark the separation between “debits” and “credits”. This is posted to the Cash T-account on the credit side beneath the January 14 transaction.
- By breaking transactions down into a simple, digestible form, you can visualise which accounts are being debited and which are being credited.
- Decreases in assets are recorded by credits, so Cash will be credited for $150.
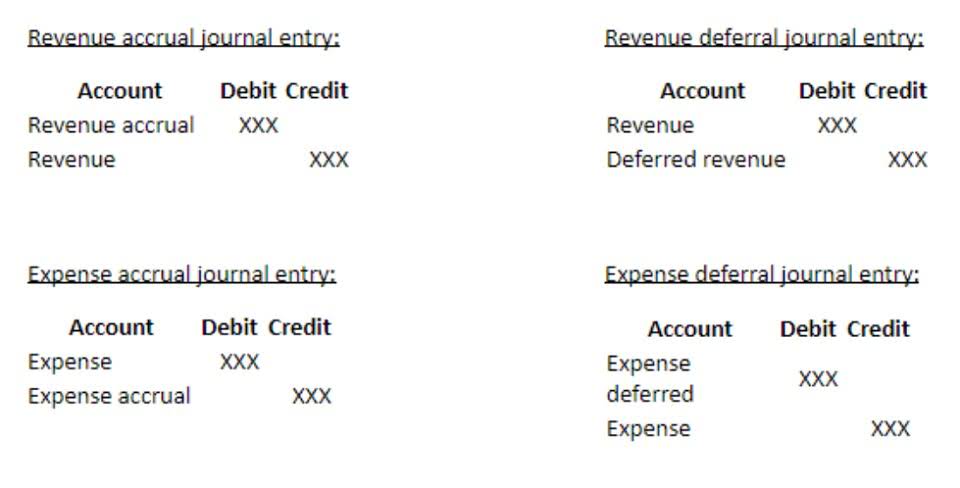
- I regularly use T-accounts when preparing adjusting entries (accruals and deferrals).
- If you’re looking to get started in business accounts, one of the best ways to do so is using a T Account template.
Comprehensive Guide to Inventory Accounting
Likewise, accounts with a credit balance, like liabilities, will always increase when another credit is added to the account. Since so many transactions are posted at once, it can be difficult post them all. In order to keep track of transactions, I like to number each journal entry as its debit and credit is added to the T-accounts. This way you can trace each balance back to the journal entry in the general journal if you have any questions later in the accounting cycle. A T-account is used to track specific transactions, while the balance sheet is a summary of a company’s overall financial position. Both statements are important tools in accounting and finance, and they are used to help stakeholders understand a company’s financial health.
- They are a visual way of recording all transactions that a company makes.
- The asset Cash also decreases and gets a credit entry of $3,200.
- The T-account is a quick way to work out the placement of debits/credits before it’s recorded in full detail to help avoid data entry errors.
- Right now, our Supplies account says we have $3,300 worth of supplies in the supply closet, but this is no longer accurate.
- The following T-account examples provide an outline of the most common T-accounts.
- When we introduced debits and credits, you learned about the usefulness of T-accounts as a graphic representation of any account in the general ledger.
Use Baremetrics to track your T accounts
Joe Smith, Drawing is a sub-account of the Joe Smith, Capital account. In this case, we want to reduce equity so we debit the account. The expense account we will use for the salaries we paid is Salaries Expense. When a business owner opens a business, they are turning personal funds into business funds. The business now owes that investment back to the business owner.
Calculating Account Balances
T accounts are one of the primary forms of performing double-entry accounting. In our next lesson we’re going to continue working with T-accounts and focus on a balance t account example very important aspect of them – learning how to balance T-accounts. The nature of each transaction can also be quickly determined. This is the same as the previous transaction, just on the opposite side – we enter the transaction on the credit (right) side of the bank T-account.
- It is a good idea to familiarize yourself with the type of information companies report each year.
- Two entries (hence, double entry), one on the left and one on the right, so everything is good.
- But before transactions are posted to the T-accounts, they are first recorded using special forms known as journals.
- So, we have our opening balance (debit) of $4,300 and our closing balance (debit) of $19,100.
- In the journal entry, Utility Expense has a debit balance of $300.
- The debit is on the left side, and the credit is on the right.
T-Accounting meets business reality
Any transaction a business makes will need to be recorded in the company’s general ledger. The general ledger is divided up into individual accounts which categorise similar transaction types together. It is beneficial if you are looking to complete a journal transaction and see how it will affect the general ledger accounts. This is posted to the Cash T-account on the debit side beneath the January 17 transaction. Accounts Receivable has a credit of $5,500 (from the Jan. 10 transaction).
Understanding Form 990: Transparency and Accountability for Nonprofits
Notice that these are account balances—not column balances. The total difference between the debit and credit columns will be displayed on the bottom of the corresponding side. In other words, an account with a credit balance will have a total on the bottom of the right side of the account. A T-Account is a visual presentation of the journal entries recorded in a general ledger account. This T format graphically depicts the debits on the left side of the T and the credits on the right side. This system allows accountants and bookkeepers to easily https://www.bookstime.com/ track account balances and spot errors in journal entries.
How are the main accounts represented in T accounts?
When a business sells to its customers, it receives cash either “now” or “later”. If cash is being received at the time of the sale, the textbook will specify “received cash” to indicate that. If the textbook says “on account” or “billed”, it means that cash will come later. When cash will be received later the account we use to track what the business will be receiving later is Accounts Receivable. Always refer to the company’s Chart of Accounts for the official name of the expense accounts. In accounting, the name must always match exactly for accuracy and clarity.